
Life insurance
Bancassurance Advisor
Built for life insurers that sell through a partner bank. The relationship manager picks the customer from the bank’s records, works out the family’s protection gap with every figure on screen, shows a recommendation with a live premium and illustration, and completes a signed digital application — accepted instantly or referred to an underwriter.
- Status
- Interactive prototype
- Updated
- October 2026
- Data
- Fictional, browser-only
- Built by
- Nityo Infotech Indonesia
The short version
Watch the workflow before you open it.
Recorded from the running prototype — every screen in the film is one you can click through yourself.
01 · The problem
Bank customers buy what they understand — and most don’t understand the brochure.
In a branch, life cover is often sold from printed illustrations and long paper forms. Customers can’t see why a product fits them, and incomplete forms come back from underwriting days later.
The prototype turns the conversation into four clear steps on a tablet, with the reasoning visible to the customer at every point.
02 · Use cases
Advice in the branch that customers understand
For any life insurer selling through partner banks, agents or financial advisers, where suitability and paperwork slow every sale.
- 01Bancassurance in bank branches
- Who
- Relationship managers selling life cover to bank customers.
- The situation
- Advice relies on printed brochures and long paper forms, and incomplete applications bounce back from underwriting.
- What changes
- A four-step tablet conversation: profile from the bank, protection gap explained, recommendation with reasons, and an application signed on screen.
- 02Suitability and affordability controls
- Who
- Compliance teams responsible for fair selling.
- The situation
- It’s hard to show that each product fitted the customer’s needs and budget.
- What changes
- Every recommendation is tied to stated goals, premiums are checked against income, and high ratios need a manager’s recorded sign-off.
- 03Agency and adviser sales
- Who
- Tied agents and independent advisers.
- The situation
- Illustrations are built in separate tools and re-keyed into application forms.
- What changes
- The same needs-to-application flow works for agents, with illustrations that update live as cover changes.
- 04Straight-through issue
- Who
- Operations and underwriting teams receiving applications.
- The situation
- Most applications are clean but still wait in the same queue as complex ones.
- What changes
- Clean applications are accepted automatically; only health declarations that need review are referred, with the reason attached.
Fits
- Life insurers with bank partners
- Agency and adviser channels
- Takaful family products
- Digital-only life products
Extends to
- Remote advice by video
- Product comparison for advisers
- Lead handover from bank apps
- Commission and sales tracking
A production build connects to
- The bank’s customer records (with consent)
- Policy administration and underwriting rules
- E-signature and identity checks
- Autodebit setup with the bank
03 · Functional highlights
What you can try
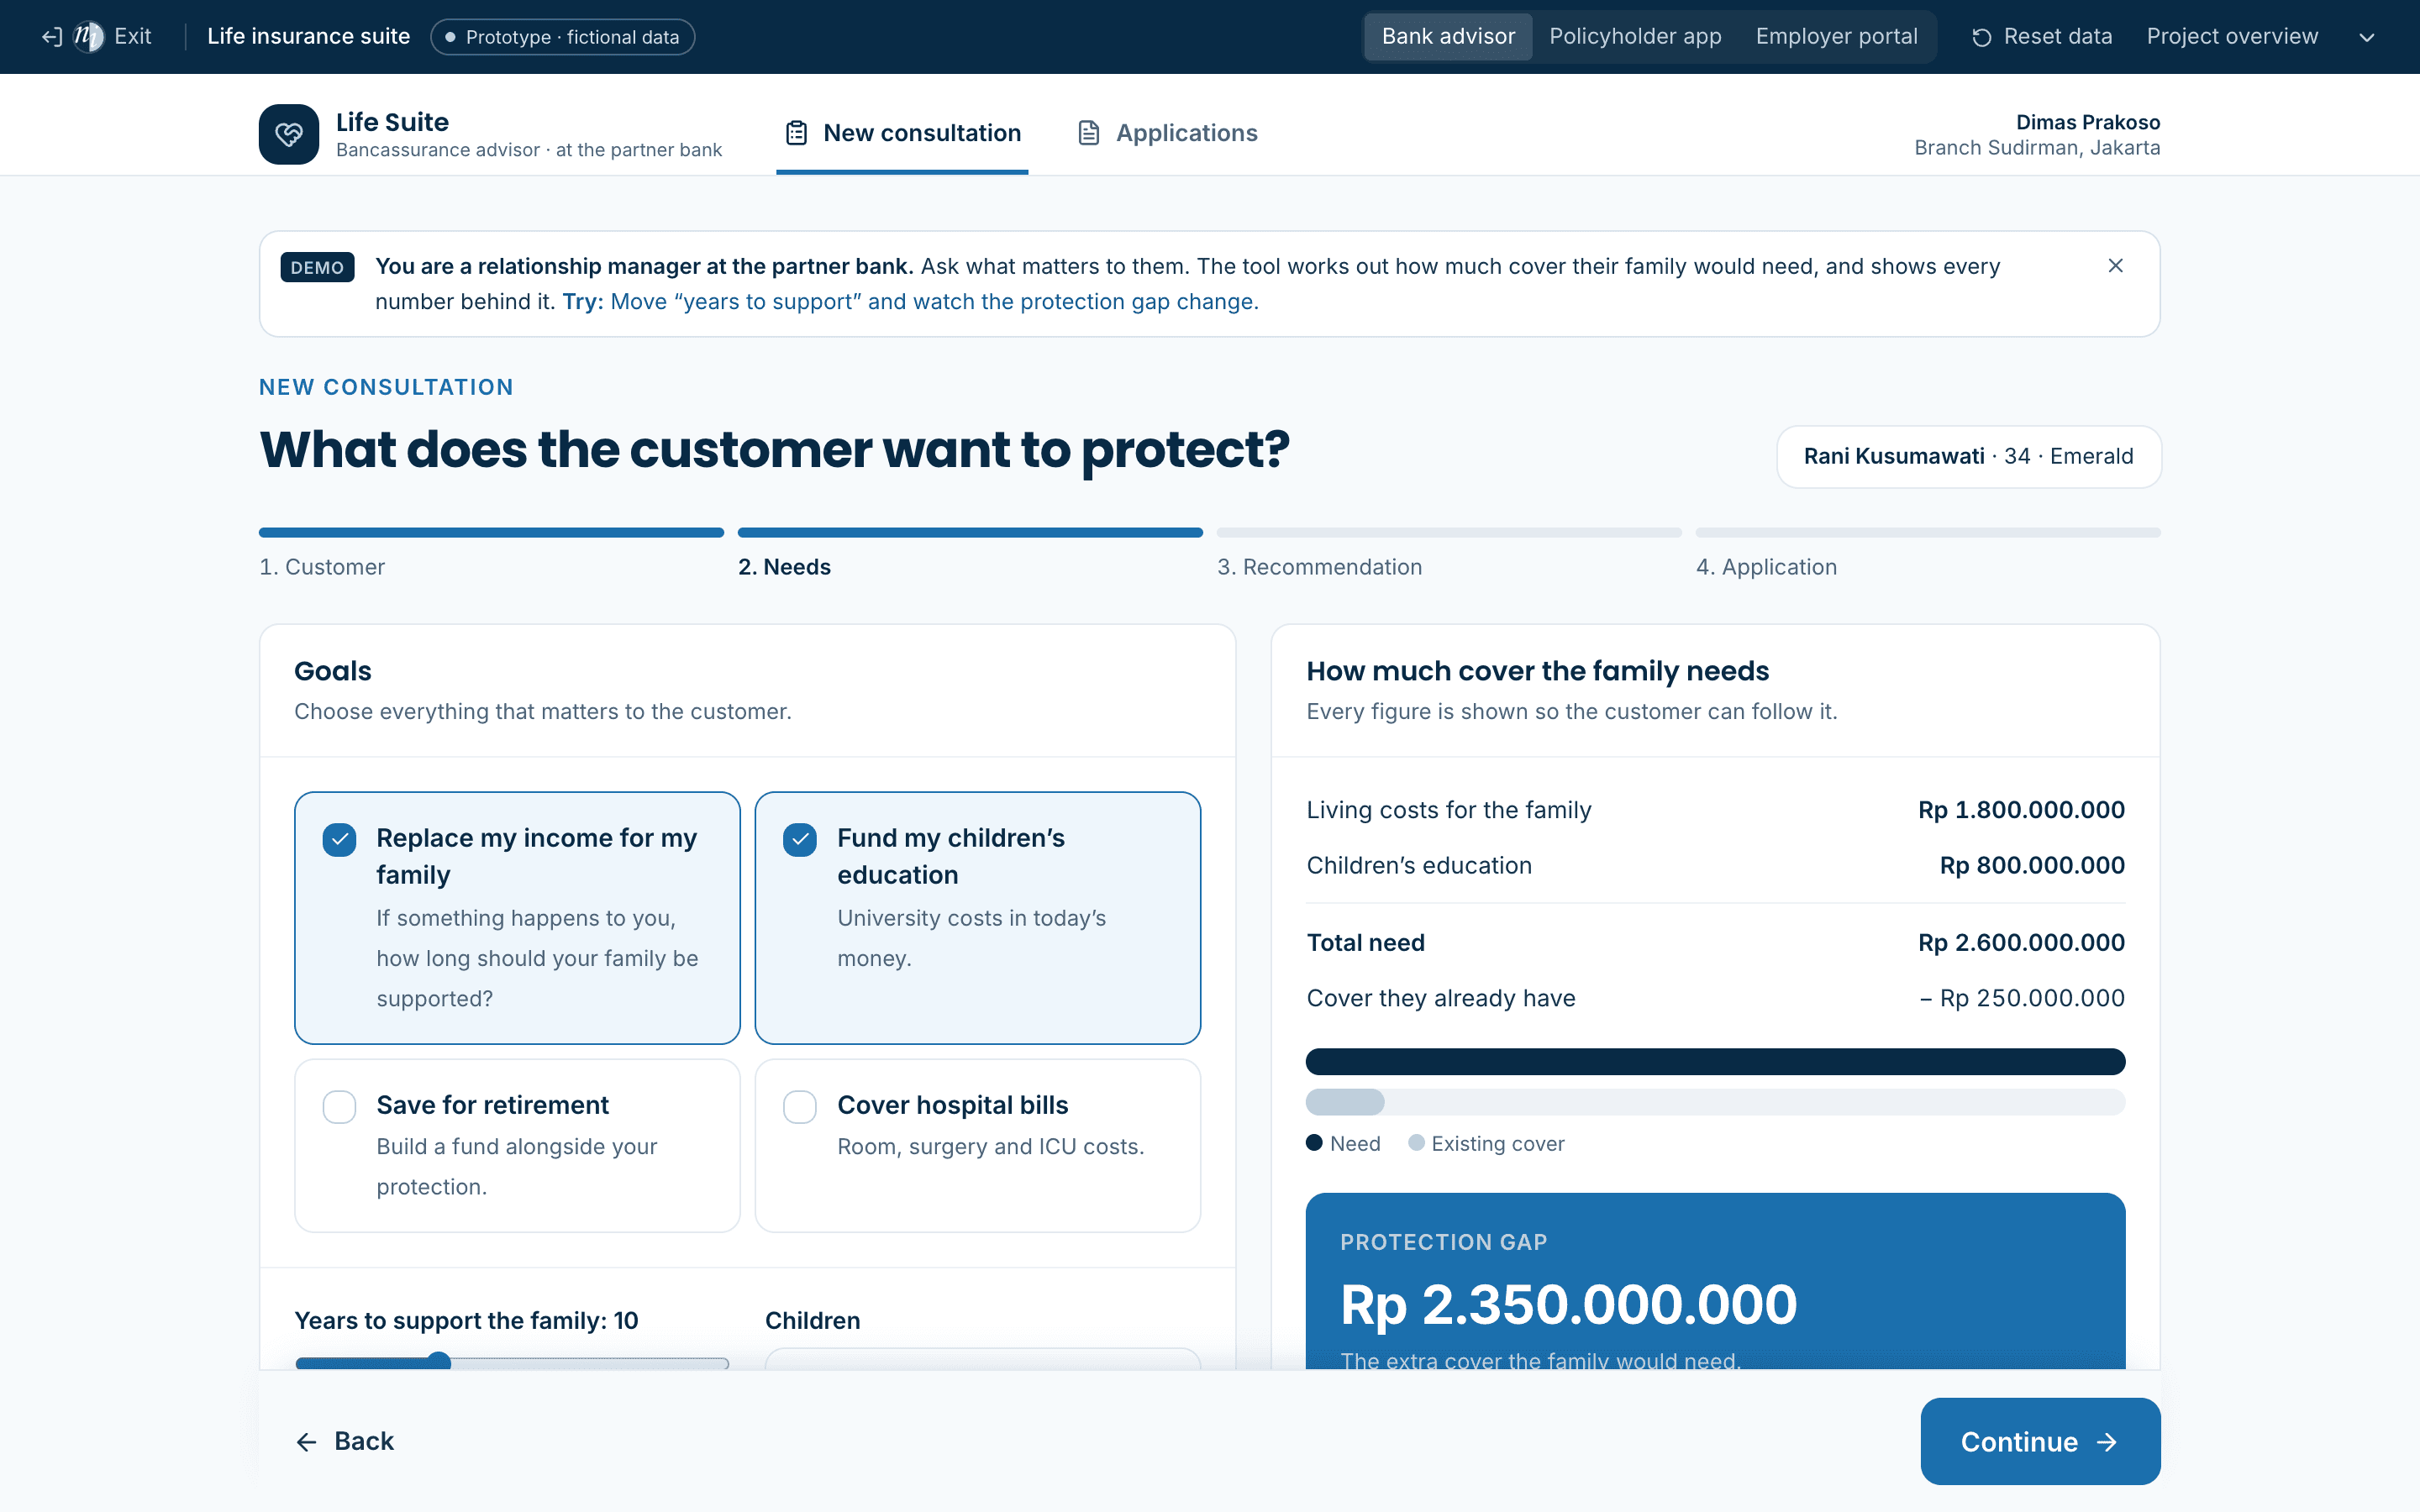
- Explained protection gap
- Living costs, education and existing cover are shown line by line, so the recommended amount is never a mystery.
- Recommendation with reasons
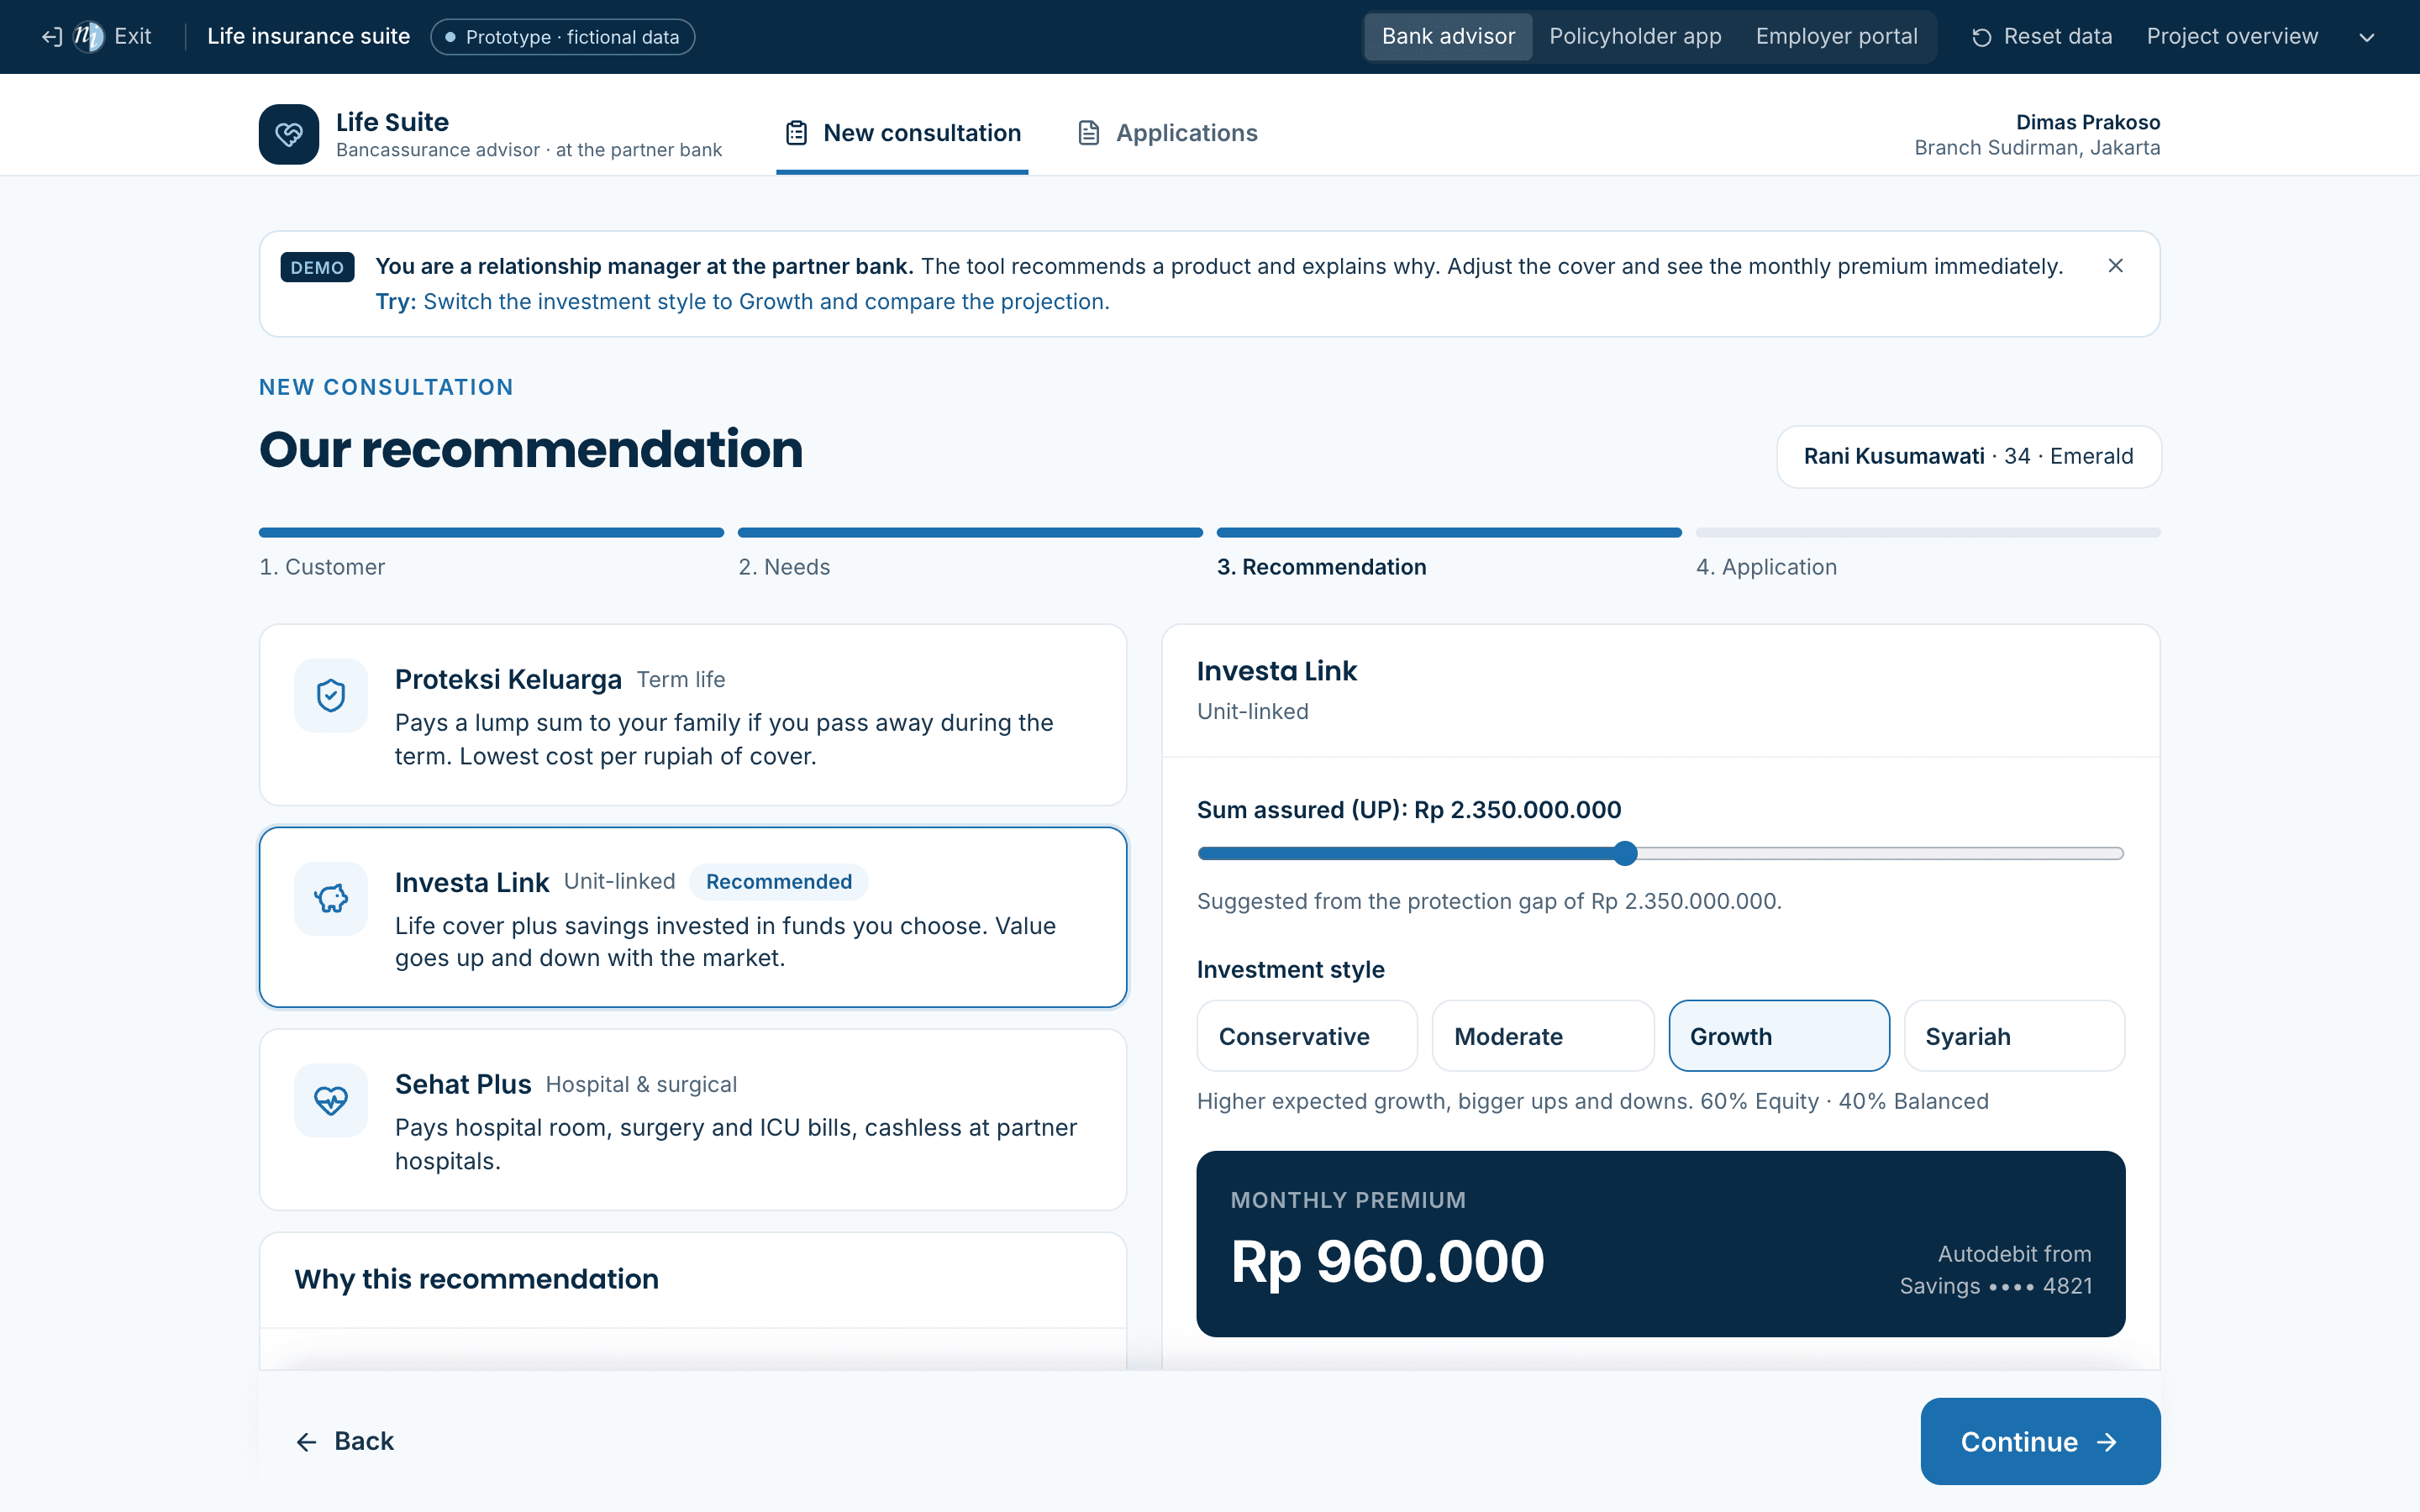
- The product is matched to the customer’s goals, with a short “why” for each one.
- Live illustration
- Change the cover or investment style and the premium and projection update immediately.
- Signed digital application
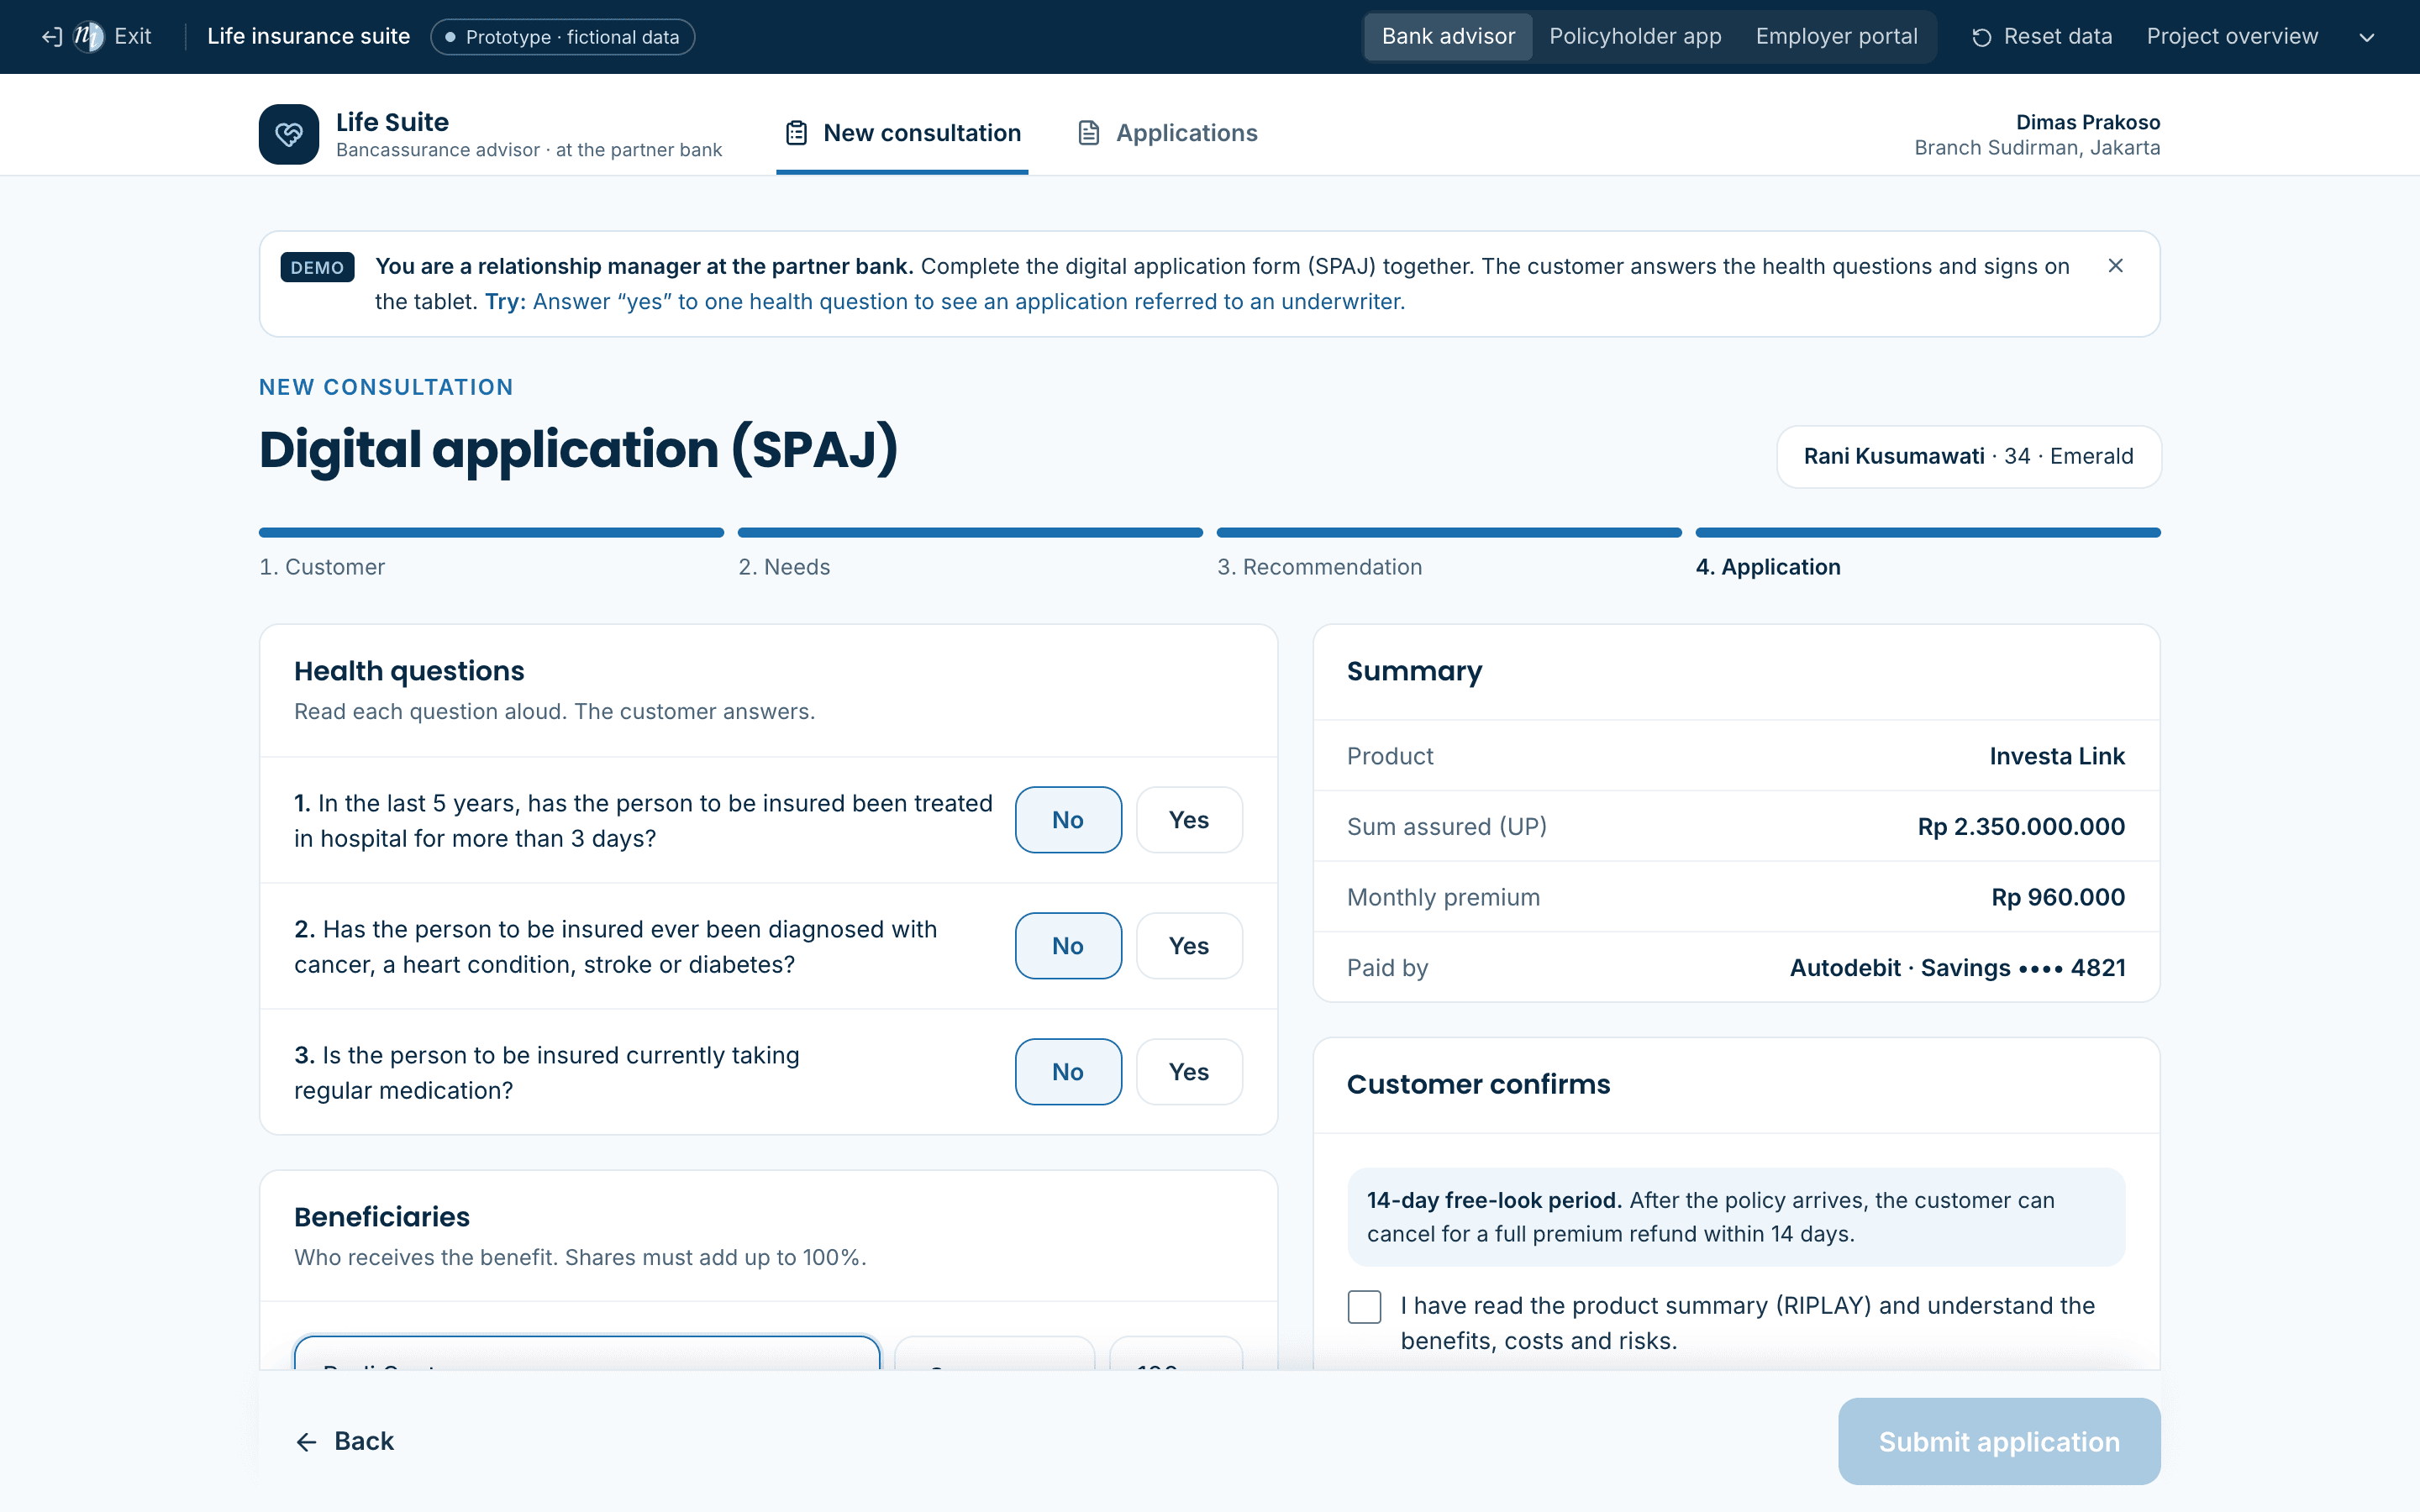
- Health questions, beneficiaries, consent and a signature — accepted instantly or referred to an underwriter.
04 · Interface previews
Captured from the running prototype
05 · Simulated versus live
What the demo simulates, and what a build would connect
| Capability | In the concept demo | In a production build |
|---|---|---|
| Customer data | Four fictional profiles | Bank CRM, with customer consent |
| Pricing and illustration | Illustrative formulas | Approved rate tables and OJK-compliant illustration |
| Signature | Drawn on the screen | Certified e-signature |
| Underwriting | Three-question rule | Underwriting engine and medical checks |
06 · Prototype limitations
What this demonstration is — and is not
- The insurer, the partner bank and every customer, employee and policy are fictional.
- Premiums, fund returns and underwriting rules are illustrative — not real tariffs or guaranteed values.
- Data stays in this browser. No identity, health, document or payment data is collected.
- No core policy, bank, payment, hospital or OJK reporting system is connected.
Try it
Open it and walk through the workflow.
- 1Pick Rani Kusumawati.
- 2Move “years to support” and watch the gap change.
- 3Choose a Growth investment style and read the illustration.
- 4Answer the health questions, sign, submit and issue.