
Insurance
Underwriting Workbench
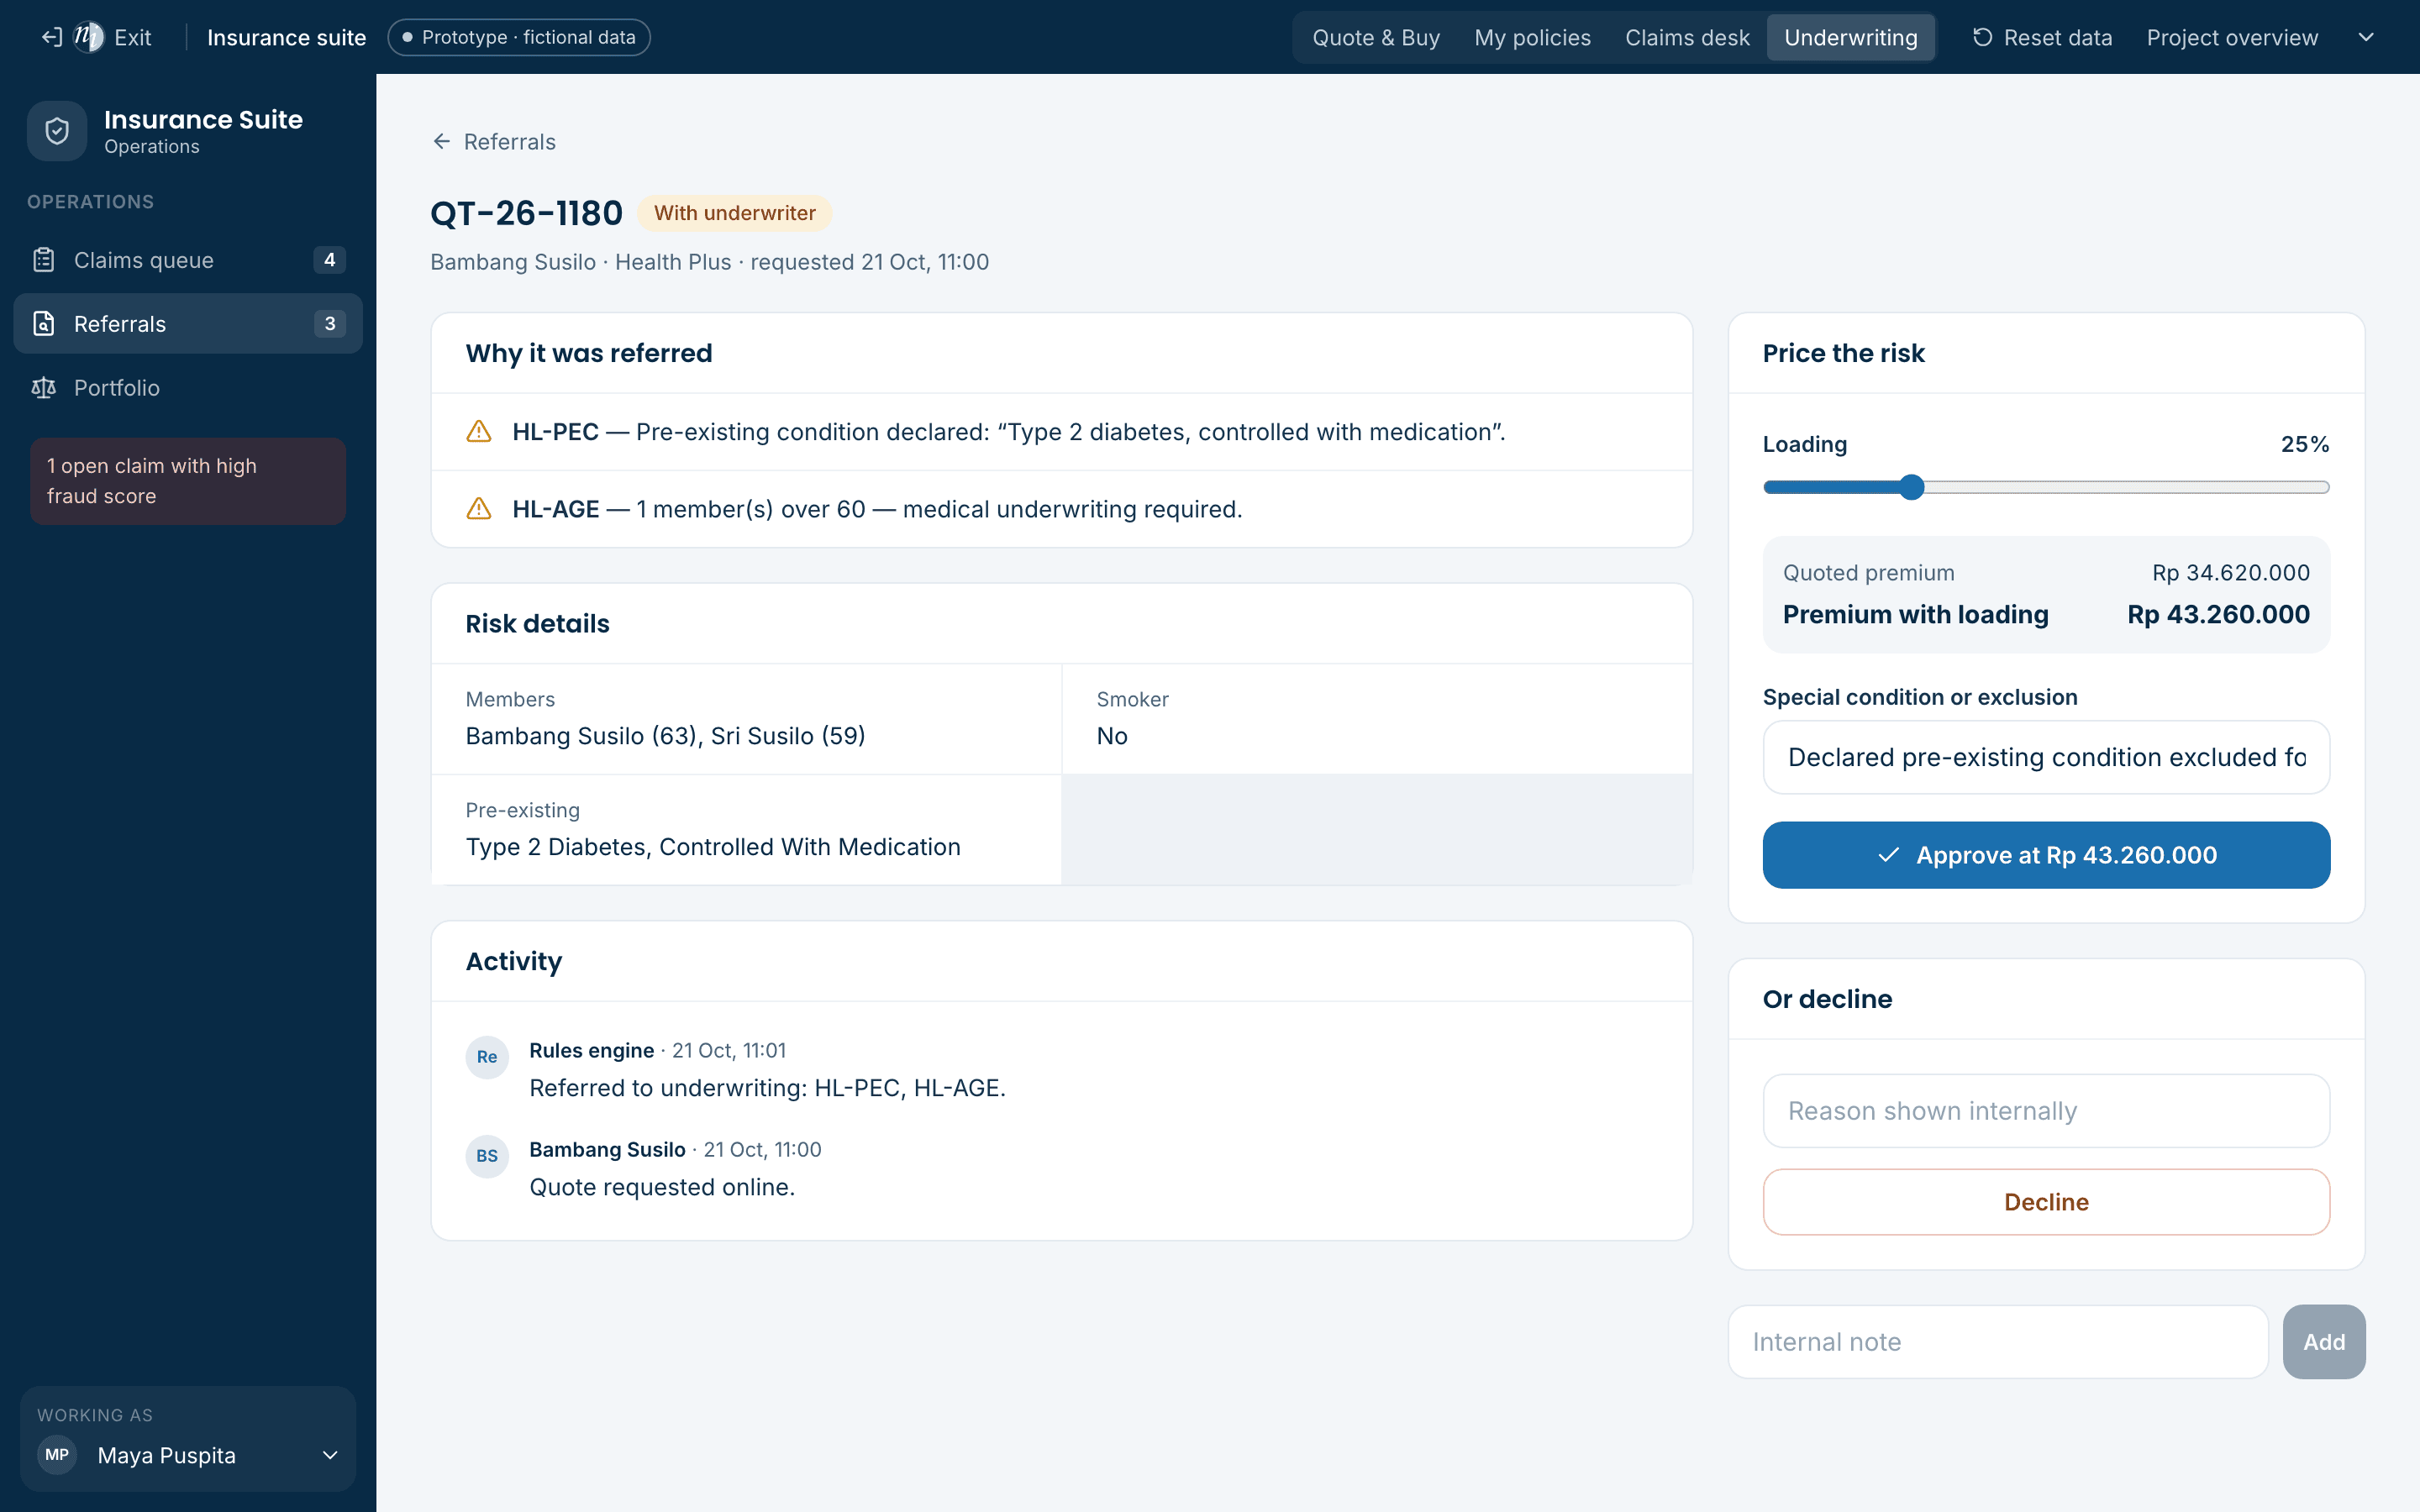
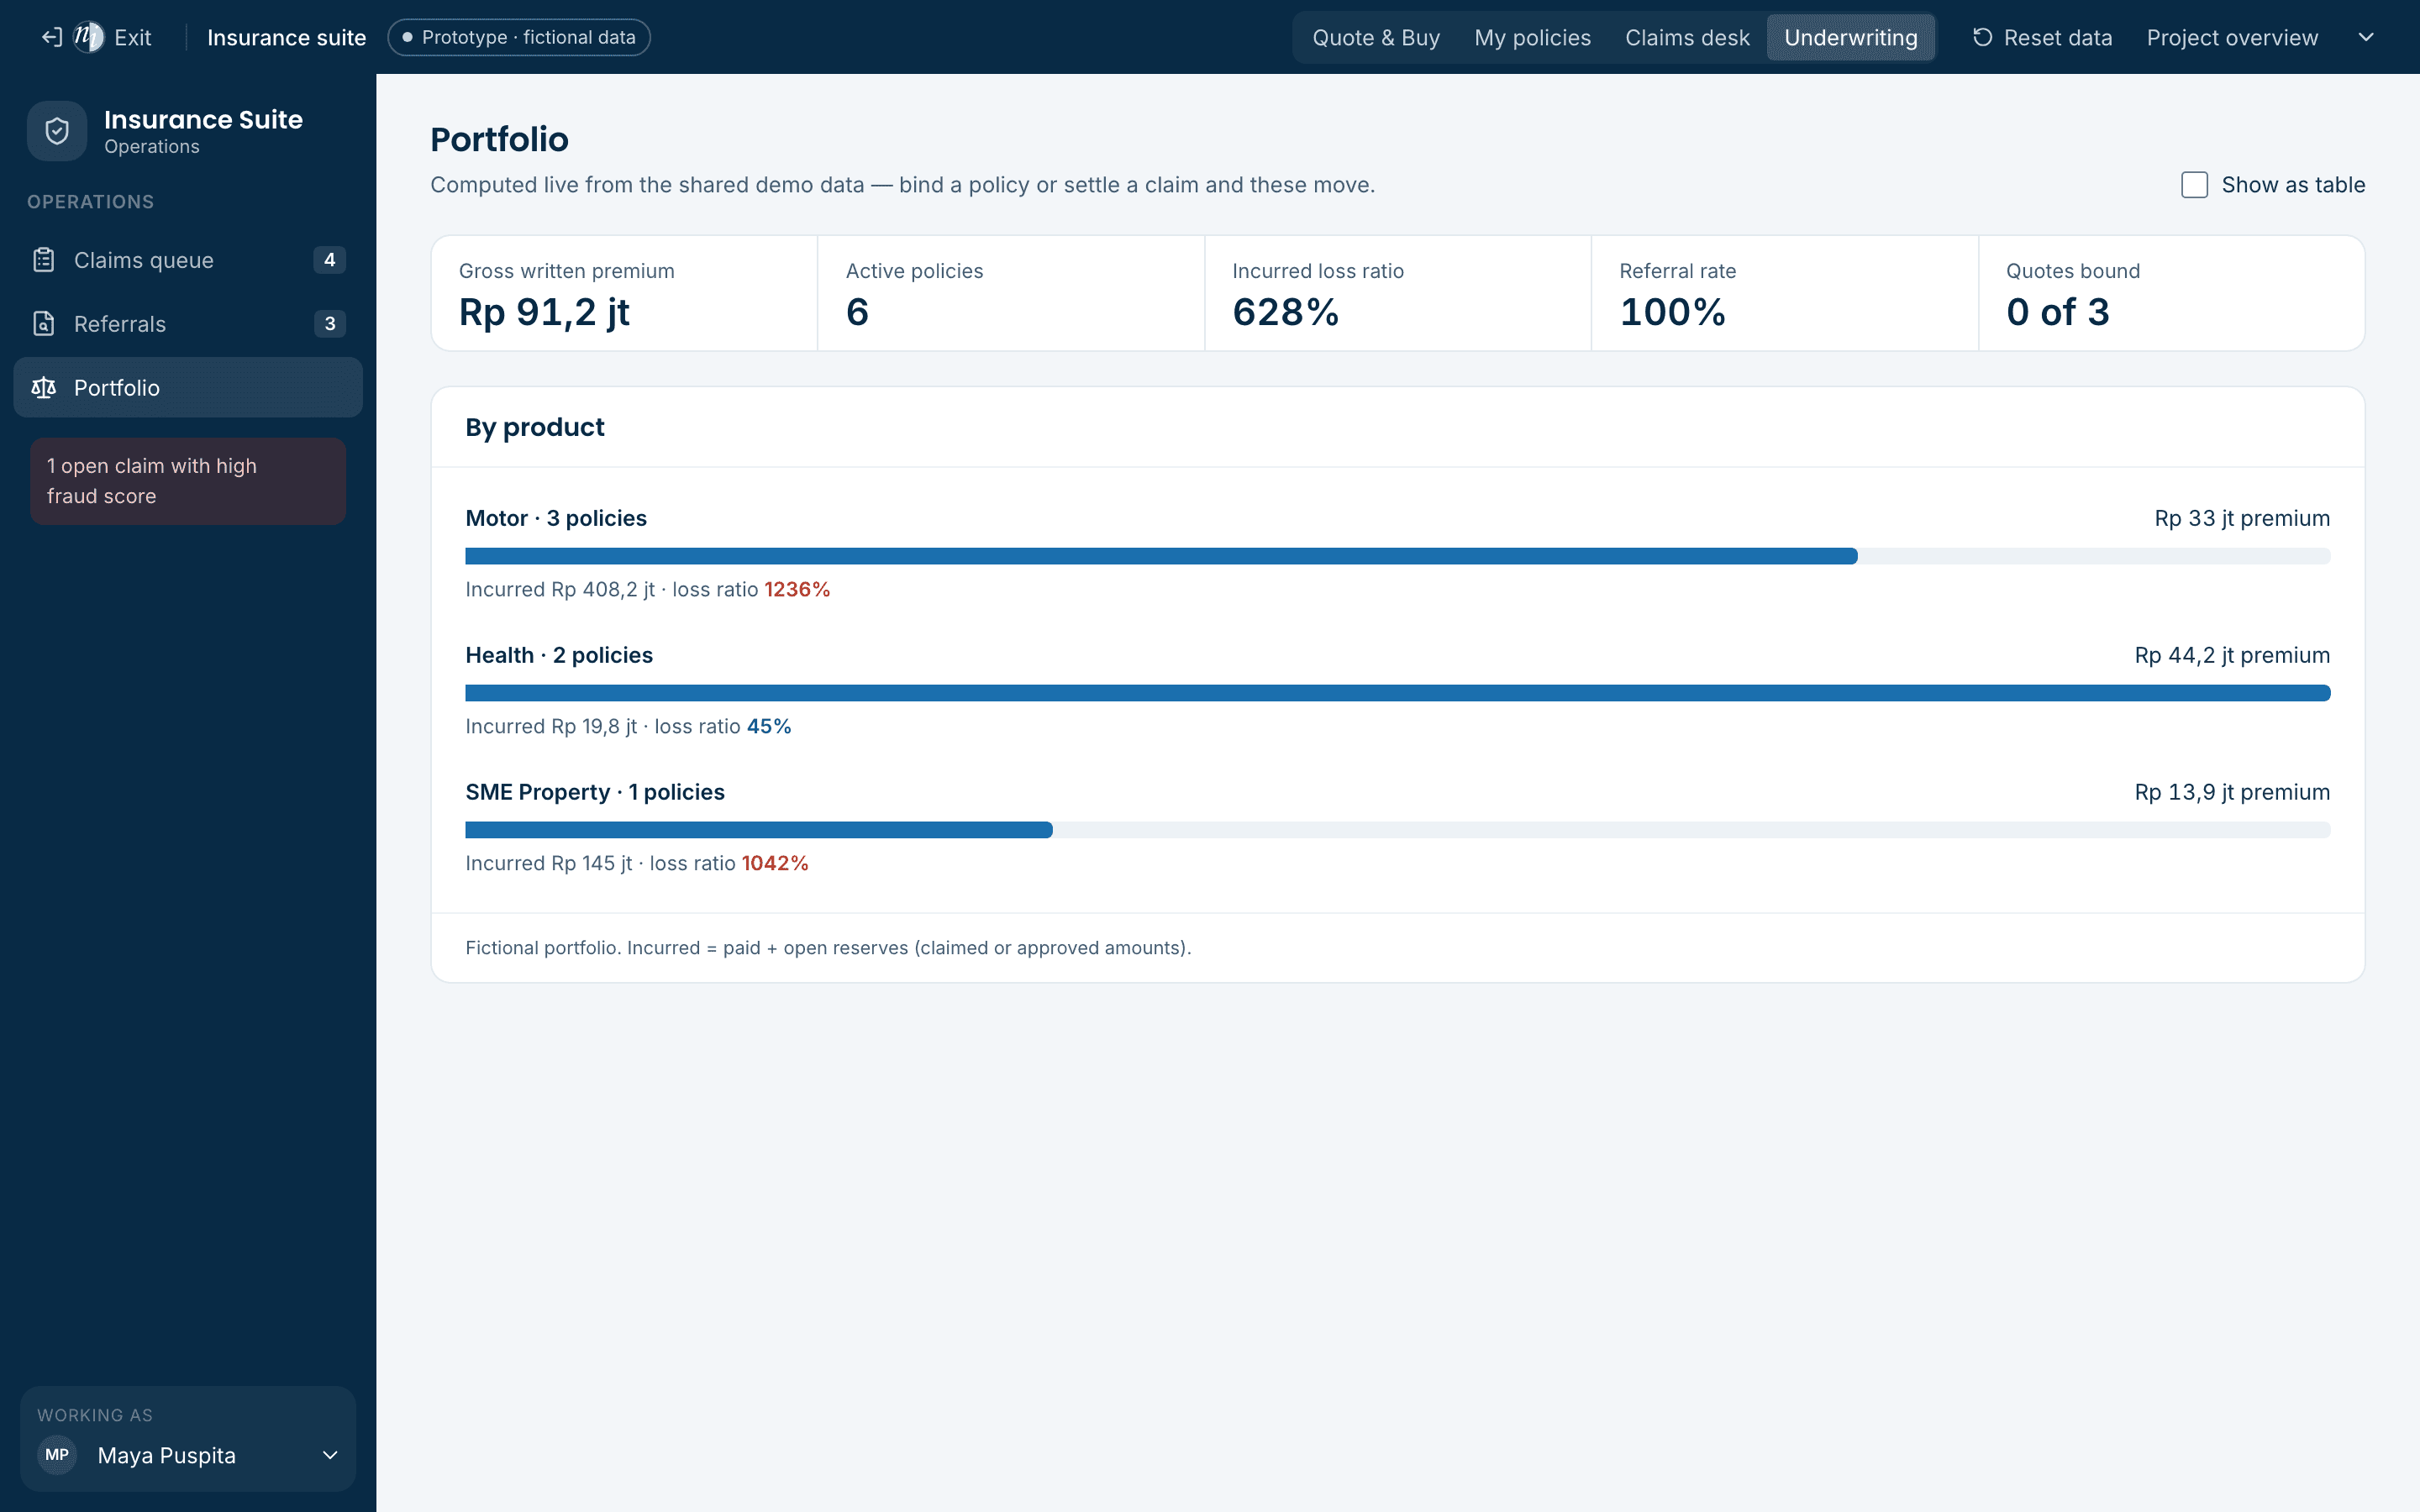
Underwriters receive only the quotes the rules engine could not accept. Each case shows why it was referred and the full risk, and the underwriter prices it with a loading or exclusion — the decision reaches the customer immediately. A portfolio view summarises premium, claims and loss ratio by product.
- Status
- Interactive prototype
- Updated
- October 2026
- Data
- Fictional, browser-only
- Built by
- Nityo Infotech Indonesia
The short version
Watch the workflow before you open it.
Recorded from the running prototype — every screen in the film is one you can click through yourself.
01 · The problem
Underwriters spend their time on the wrong cases.
When every non-standard quote arrives as an email, underwriters re-read the same forms and re-key the same numbers, and the referral reason is often missing.
The prototype sends only rule-triggered quotes to underwriters, explains why each one is there, and turns the decision into a single priced action that the customer sees straight away.
02 · Use cases
Underwriters on the cases that need them
For any insurer where referrals arrive as emails and underwriters spend their time re-reading forms rather than judging risk.
- 01Referral queue for retail products
- Who
- Underwriting teams handling motor and health referrals.
- The situation
- Referred quotes arrive without a clear reason and get re-keyed into a rating sheet.
- What changes
- Only rule-triggered quotes reach the queue, each says why it was referred, and pricing happens on the case itself.
- 02Pricing with a loading or exclusion
- Who
- Underwriters accepting non-standard risks.
- The situation
- Loadings are calculated in spreadsheets and emailed back to sales, who tell the customer days later.
- What changes
- Move the loading and the premium re-prices live; the decision reaches the customer’s quote at once, ready to buy.
- 03Turnaround and service levels
- Who
- Underwriting managers with service commitments to brokers.
- The situation
- Nobody can see which referrals are about to breach the agreed turnaround.
- What changes
- Every referral shows the time left against the target, so the team works the oldest and riskiest first.
- 04Portfolio oversight
- Who
- Heads of underwriting and actuarial teams.
- The situation
- Written premium and loss ratios come from monthly reports, long after decisions are made.
- What changes
- Premium and loss ratio by product are computed from the same records the decisions are made on.
Fits
- General and health insurers
- Managing general agents
- Reinsurance-backed programmes
- Commercial lines teams
Extends to
- Medical underwriting questionnaires
- Authority levels by underwriter
- Rule management for business users
- Reinsurance cession checks
A production build connects to
- The rating engine
- Policy administration
- Medical and credit data providers
- Data warehouse for reporting
03 · Functional highlights
What you can try
- Referral reasons
- Each case lists the rule codes that fired, in plain language.
- Loading slider
- Premium re-prices live from the same engine the customer journey uses.
- Conditions and exclusions
- Approve with a special condition that appears on the customer’s quote.
- Portfolio view
- Gross written premium, incurred claims and loss ratio by product, from the shared record.
04 · Interface previews
Captured from the running prototype
05 · Simulated versus live
What the demo simulates, and what a build would connect
| Capability | In the concept demo | In a production build |
|---|---|---|
| Rules engine | Eight illustrative rules | Your underwriting guidelines, configurable |
| Pricing | Illustrative rates | Actuarial rating and authority limits |
| External data | None | Vehicle, medical and hazard data sources |
| Reinsurance | Not modelled | Treaty and facultative checks |
06 · Prototype limitations
What this demonstration is — and is not
- The insurer and every customer, policy and claim are fictional.
- Rates, rules and fraud weights are illustrative — not real tariffs or regulatory pricing.
- Data is stored in this browser only; no documents, medical or payment data are collected.
- No core policy system, payment gateway, workshop network or regulator portal is connected.
Try it
Open it and walk through the workflow.
- 1Open the health referral for a 63-year-old with diabetes.
- 2Move the loading slider and watch the premium re-price.
- 3Approve with an exclusion; check the customer’s quote in My policies.
- 4Open Portfolio — bind the policy and the premium figures move.